There are times when selling a property changes from a strategic choice into a necessity. The reasons may include a need for cash, inheritance, separation, an underperforming investment or changing housing needs. The market often interprets such situations mainly in financial terms, as though every decision were a rational comparison of costs and benefits.
The reality is more complex.
Property professionals regularly see informed owners refuse market-level offers, leave homes unsold for years or sell valuable assets at an unfavourable moment. If financial rationality alone guided decisions, these situations would be unusual. They are, in fact, common.
Decision-making psychology offers another way to understand them.
Over the last forty years, behavioural finance has changed how economists understand investors. Daniel Kahneman’s 2002 Nobel recognition highlighted the influence of emotions, mental shortcuts and perceptual biases on decisions, challenging the rational behaviour assumed in traditional models.
Richard Thaler’s work further developed this perspective. The article draws on these ideas to consider how avoiding emotional discomfort can influence decisions about property.
A home is more than an entry on a family balance sheet. It holds memories, relationships, effort, plans and identity. Each room and renovation reflects personal choices and reinforces attachment, making it harder to view the property only as a financial asset.
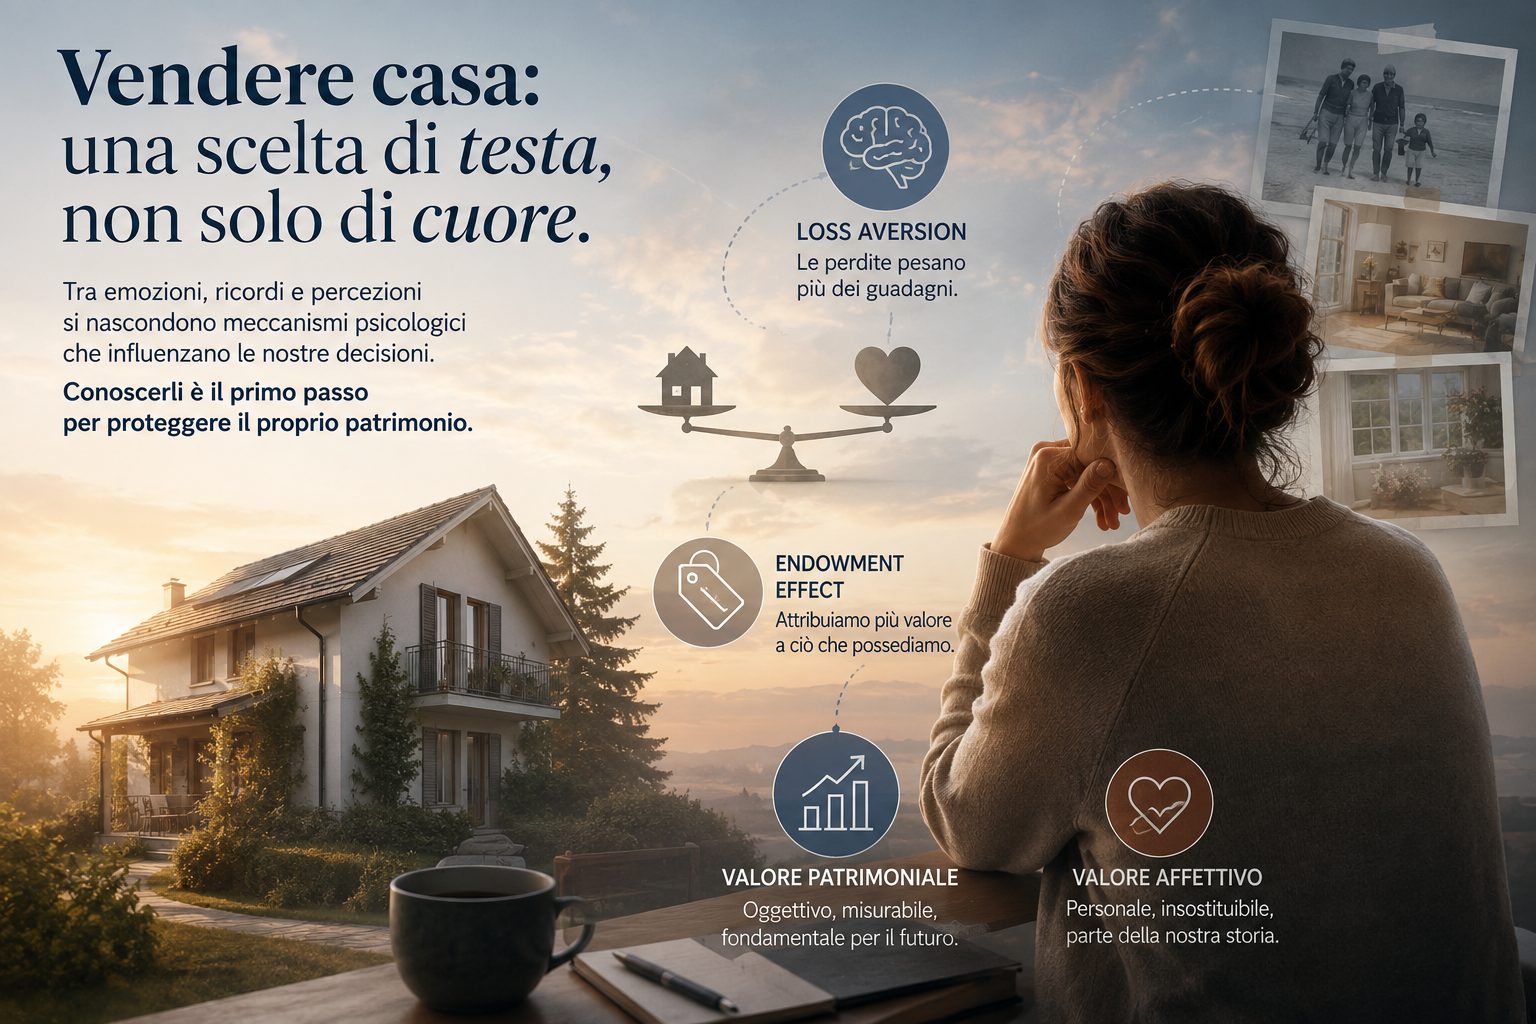
One relevant contribution is Prospect Theory, developed by Daniel Kahneman and Amos Tversky in the late 1970s. It describes how losses can carry more psychological weight than equivalent gains: losing a hundred thousand euros can feel more painful than the pleasure of gaining the same amount.
This asymmetry, known as Loss Aversion, can also affect property decisions. When value falls below expectations, owners may delay selling to avoid the emotional discomfort of acknowledging a loss.
While the property remains theirs, a hoped-for recovery or a buyer willing to pay the desired price still feels possible. Lowering the asking price can make a potential loss feel final, creating resistance stronger than the financial argument.
This helps explain why homes can remain on the market with unrealistic asking prices. Owners may understand the market but find its message difficult to accept.
The market sees a transaction; the owner may experience a sense of loss.
Another mechanism discussed by Richard Thaler is the Endowment Effect, the tendency to value something more highly because we own it.
A home valued by the market at four hundred thousand euros may feel worth considerably more to its owner because it represents years of work, investment and personal memories. Those feelings become part of the owner’s assessment.
The property’s market value has not necessarily increased; its personal meaning has.
This distinction has practical consequences. Owners may reject reasonable offers because they compare them with the property’s emotional value.
The opposite can happen too. Fear, uncertainty or an urgent need for money may prompt a sale at a poor moment, with the decision driven more by relief from pressure than a balanced assessment of future options.
Some properties sold during periods of personal or family strain later increase in value. The issue may have been less a lack of information than a lack of time or emotional space to weigh the choice.
This connection between belonging and financial value makes property decisions different from many other investments. A home often remains part of our identity long before it is considered an asset.
Managing property strategically requires distinguishing personal attachment, which is legitimate and irreplaceable, from financial value, which calls for as much objectivity as possible. Financial decisions affect the preservation of wealth, future opportunities and what can be passed on to the next generation.
Confusing these dimensions can lead to decisions that feel reassuring emotionally but work less well financially.
Perhaps the most useful lesson is that homes are sold or retained not only when markets change, but when people change.
A thoughtful property decision therefore considers both what a home is worth and how our relationship with it shapes the choices we make.