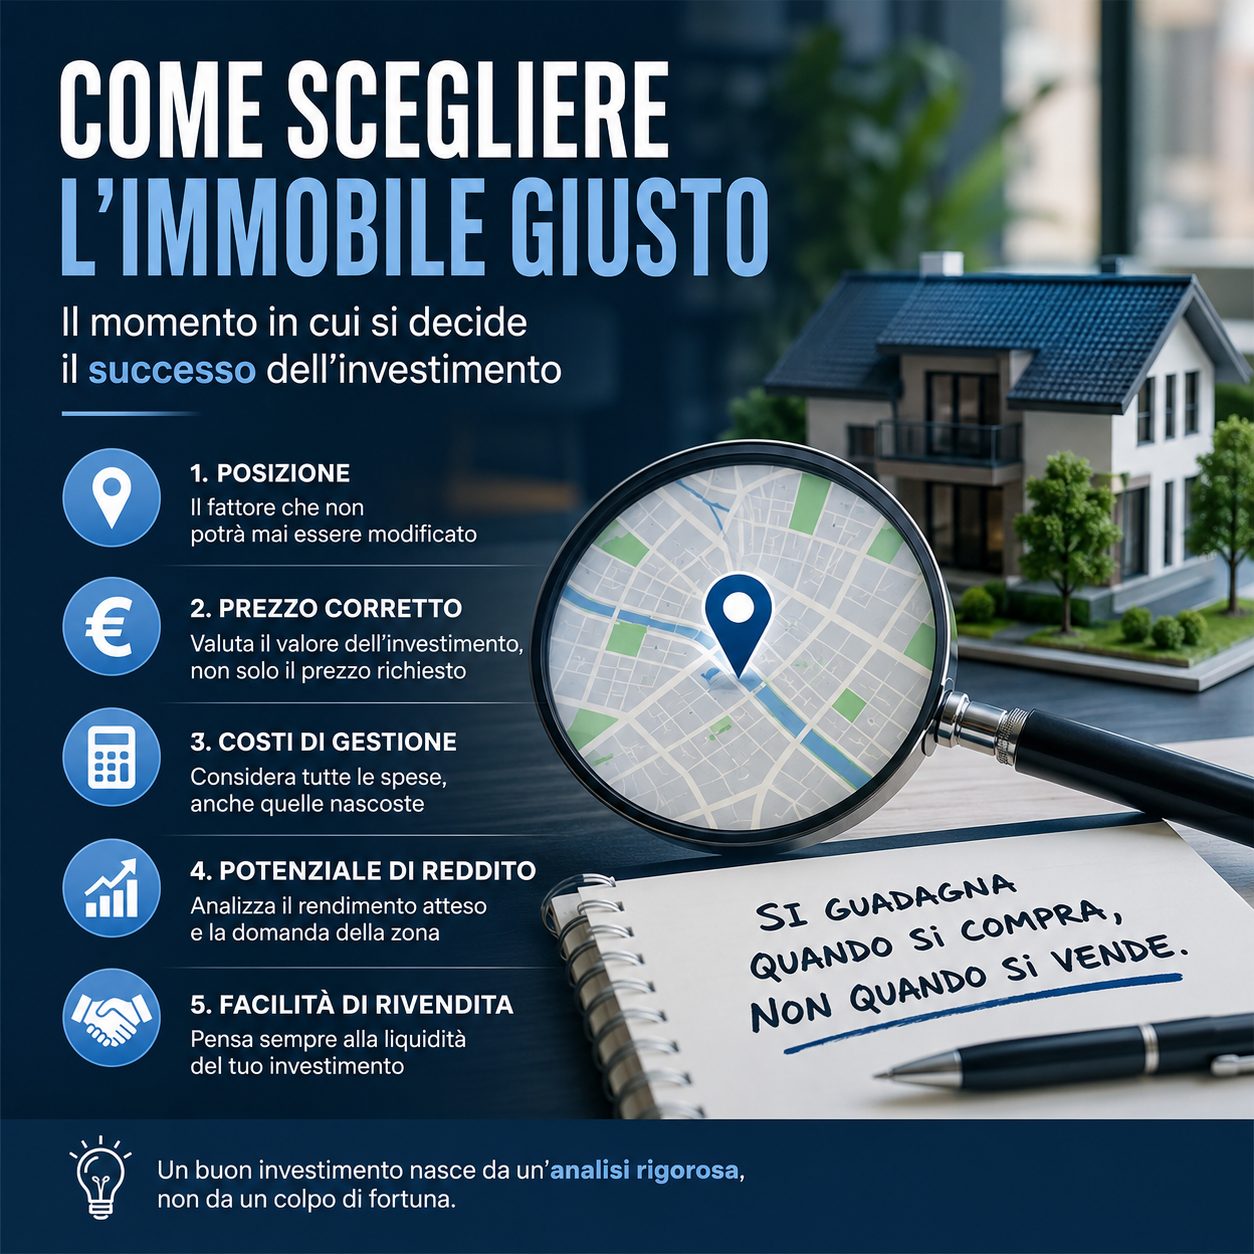
A familiar saying among property investors is also frequently misunderstood:
“You make your profit when you buy.”
Selling at the right time and managing a property well both matter, but they are later stages of the investment process.
Much of the eventual result depends on the initial decision: whether to buy and, above all, at what price.
A sustainable investment is less about luck than method, analysis and discipline.
From homebuyer to investor: a change of perspective
When choosing a home to live in, emotions and personal preferences naturally matter.
An investor needs to ask different questions.
Instead of asking only:
“Do I like this property?”
Ask:
“Could this property produce a sustainable return over the next 10 or 15 years?”
That shift changes the decision-making process.
The aim is a suitable balance of risk, return and growth potential rather than an imagined perfect property.
Five factors to assess
Each investment should be assessed against fundamental factors.
1. Location
Location remains crucial.
This means understanding actual demand, not simply choosing the city centre.
Consider:
- public transport connections;
- proximity to schools, hospitals and universities;
- local services and shops;
- the area's development prospects;
- rental demand and typical selling times.
A suitable location can support lettability, resale liquidity and resilience, though it does not remove market risk.
2. The full investment cost
Focusing only on the asking price misses part of the picture.
The purchase price is only one part of the investment.
Also include:
- taxes;
- notary fees;
- agency fees;
- refurbishment;
- furnishings;
- certification;
- technical professional fees;
- and financing costs.
A meaningful return calculation requires the total cost.
3. Running costs
Even a well-priced purchase can disappoint if running costs are too high.
Assess:
- condominium charges;
- ordinary maintenance;
- major repairs;
- insurance;
- taxes;
- vacant periods;
- and administration costs.
What matters is the net income, not a theoretical headline figure.
4. Income and returns
A realistic business plan is essential.
Estimate cautiously:
- achievable rent;
- occupancy;
- annual expenses;
- net yield;
- and the time needed to recover the invested capital.
Overoptimistic assumptions are a common cause of disappointment.
5. An exit strategy
Consider a possible exit before buying.
Ask:
- How easy might resale be?
- How active is the local market?
- Who could the future buyer be?
- What might support or undermine value over time?
Thinking about resale early can improve flexibility and help identify risk.
Common mistakes
Less experienced investors often repeat certain mistakes.
Examples include:
- buying on enthusiasm rather than evidence;
- underestimating taxes, fees, furnishings and other costs;
- using overoptimistic business plans;
- ignoring future major condominium works;
- not examining the rental market;
- having no contingency reserve;
- and buying without a clear exit strategy.
An incomplete initial assessment can be as damaging as an adverse market.
Using a consistent scoring method
One approach I find useful is to score each property consistently before deciding.
For example, give a score from 1 to 10 to factors such as:
- location;
- condition;
- the surrounding environment;
- rental demand;
- expected yield;
- running costs;
- potential appreciation;
- ease of resale;
- and risk.
This produces a more structured view of the investment.
Using the same criteria helps compare different properties and reduces the weight of emotion. The scores still depend on the quality of the evidence and assumptions.
Evidence before emotion
The most beautiful home is not necessarily the most profitable.
The apparently cheapest can become the most expensive over time.
A sound assessment balances acquisition cost, income, affordable running costs and future prospects.
Emotions help us choose a home to live in.
Financial evidence helps us assess an investment intended to last.
A successful investment is not simply a lucky purchase.
It depends on careful analysis, reliable evidence and decisions that remain rational when enthusiasm runs high.
Spending more time on analysis before signing an offer can help avoid costly mistakes and improve the long-term result.
The best opportunity is not necessarily the most striking property or the lowest asking price.
It is a property with a credible basis for value, sustainable income and lasting appeal, recognising that outcomes are never guaranteed.
When you assess a property, what do you consider first?